Facebook
 X
 Pinterest
 Copy Link
This is a recurring series of blog posts taking a closer look at the U.S. economy and several major regional markets in Windermere’s nine-state footprint. Updates will be released on a quarterly basis.
Economic Overview
The U.S. economy continued its streak of impressively resilient growth in the third quarter of 2026, despite higher energy costs from the war in Iran rippling through the economy. But that growth has come at a cost: higher interest rates. A perfect storm of inflation, large fiscal deficits, and competing demands for capital from the AI investment boom conspired to push the 10-year Treasury yield from an average of 4.47% in June to 4.99% in September, with no signs of cooling in sight.
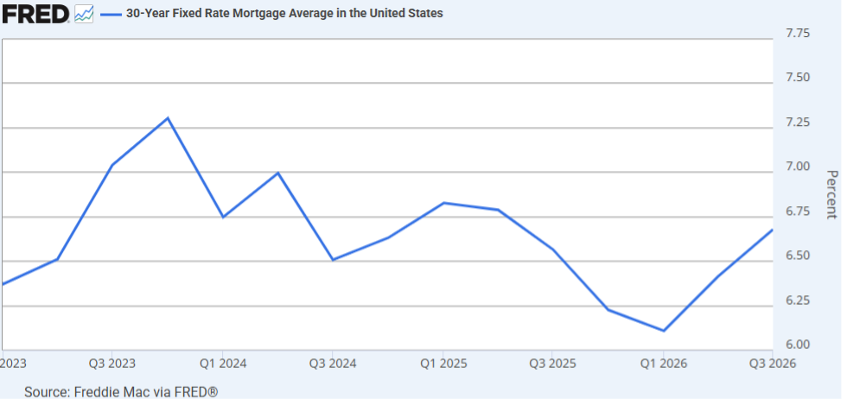
Higher Treasury yields translate directly into higher borrowing costs for homebuyers. Mortgage rates averaged 6.68% in the third quarter, up from 6.41% in the second quarter and 6.11% in the first. Meanwhile, weekly mortgage rate averages soared above 7.25% by the end of the quarter, a level not seen since 2023.
Source: Freddie Mac via FRED.
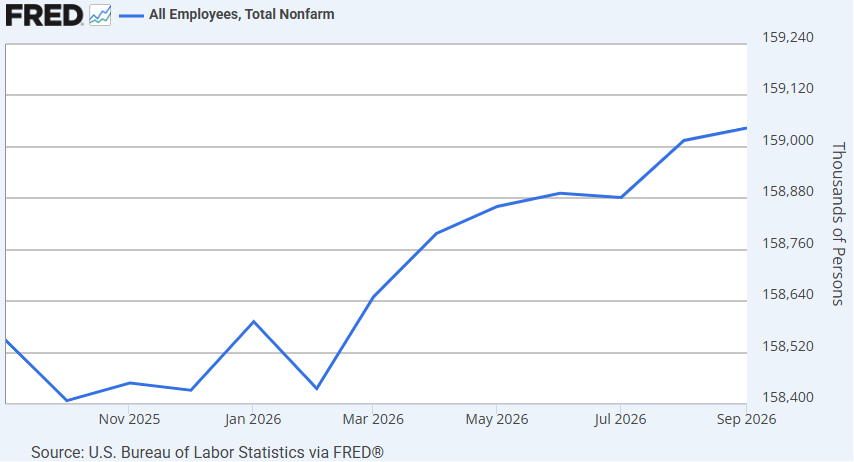
Payrolls continued to climb in the third quarter, although at a slower pace than earlier this year. Nonfarm employment totaled 159,044,000 jobs at the end of September, an increase of 152,000 from the end of the second quarter. That’s down from the 242,000 jobs added in Q2 and the 218,000 added in Q1. The slowdown may be an early sign of cooling demand for workers as companies grapple with higher costs for everything from fuel to interest on loans.
While the housing market weathered the early headwinds of rising mortgage rates during the spring selling season, cracks began to show in the third quarter. Inventory growth accelerated in many markets, while sales activity and price gains slowed or declined. High home prices and borrowing costs have kept affordability stretched to the limit, and increases in mortgage rates during the third quarter pushed homeownership even further out of reach for many buyers who might have otherwise purchased a home in the summer or fall. Looking ahead, growing inventory will continue to put pressure on sellers to cut prices while giving buyers more options and greater negotiating power.
The following is a detailed overview of housing trends across six regional markets within Windermere’s footprint during the third quarter of 2026. They include:
- Greater Seattle Area
- Greater Portland Area
- Greater Sacramento Area
- Northwest Washington State
- Spokane, WA and Coeur d’Alene, ID markets
- Salt Lake County, UT
Greater Seattle Area (King, Snohomish, Pierce, and Kitsap Counties)
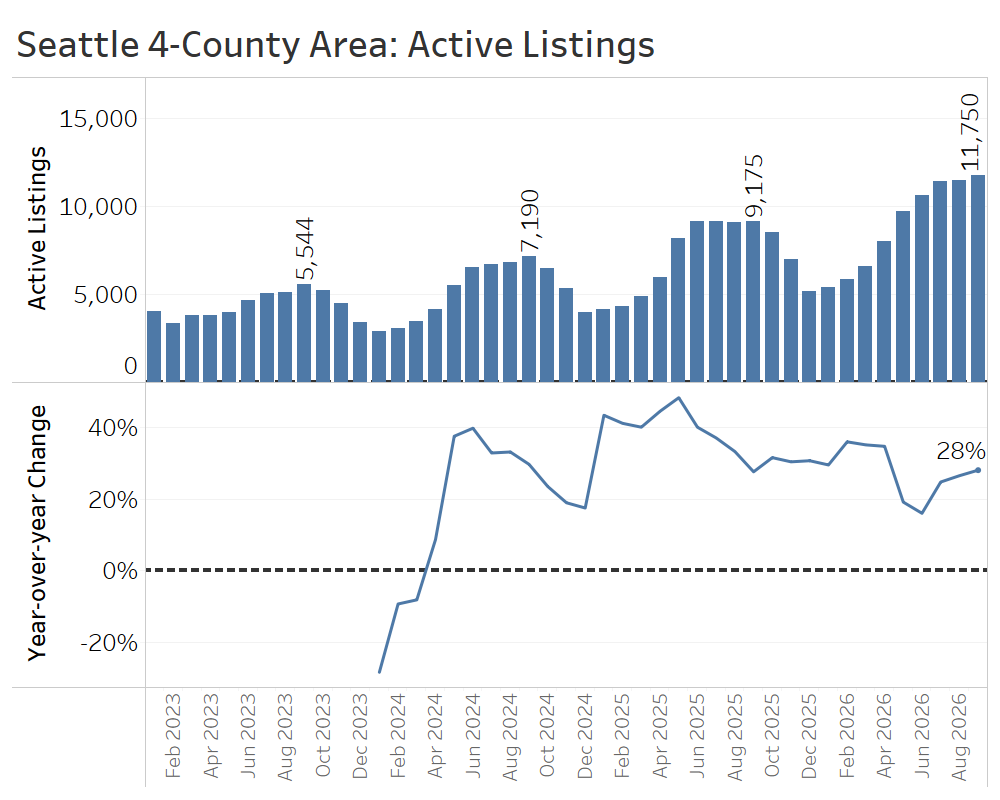
The greater Seattle area housing market swung further in buyers’ favor in the third quarter. Active listings reached 11,750 in September, 28% above their year-ago level, and more than double the level seen in September of 2023. The larger pool of listings has given buyers substantially more choice and has put even more pressure on sellers’ agents to price and present homes competitively. Not only did inventory rise, but the year-over-year pace of gains actually accelerated through the quarter.
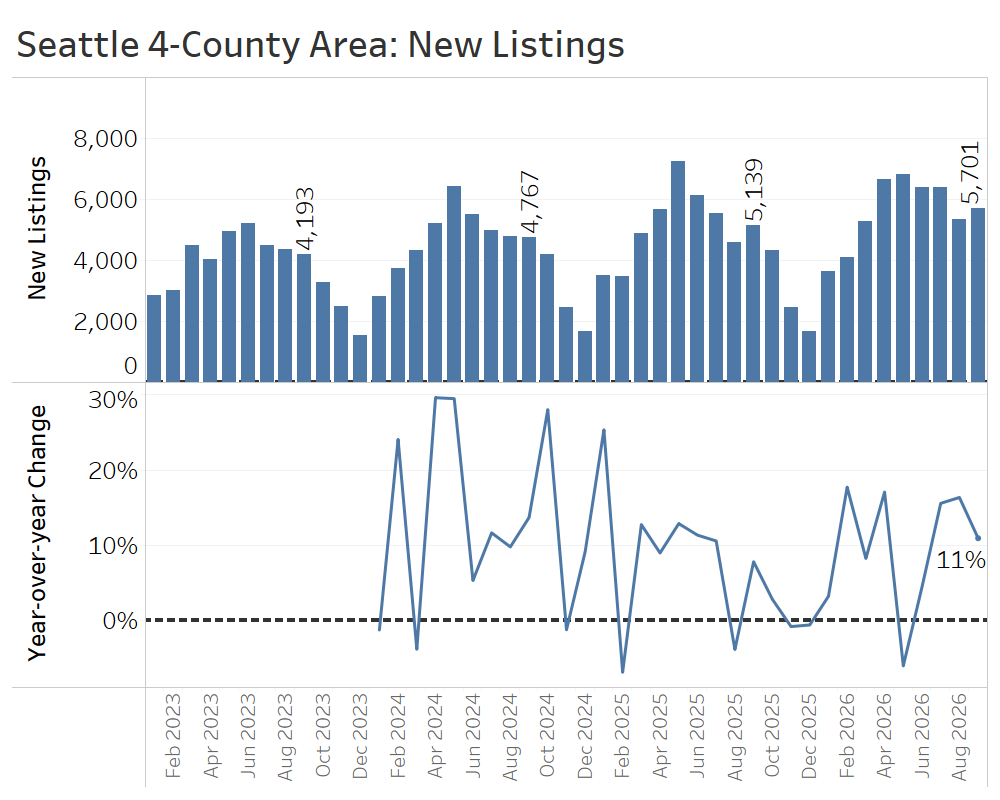
New listings also remained elevated in the third quarter. September saw 5,701 new listings, up 11% from a year earlier, while new listings for the quarter as a whole were up 14% compared with the third quarter of 2025. This sustained flow of new listings is helping drive up active inventory.
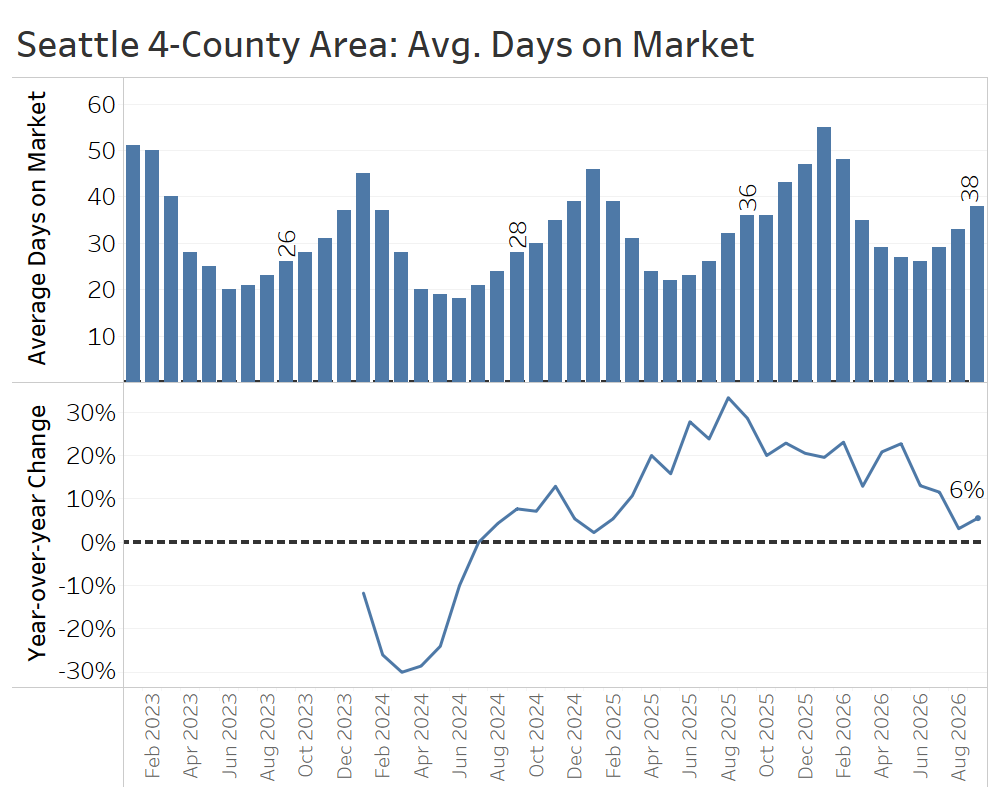
Average days on market increased during the third quarter, following a typical seasonal uptick from 29 days in June to 38 days in September. September’s average time on market was two days slower than a year earlier, reflecting the modestly softer demand and elevated supply.
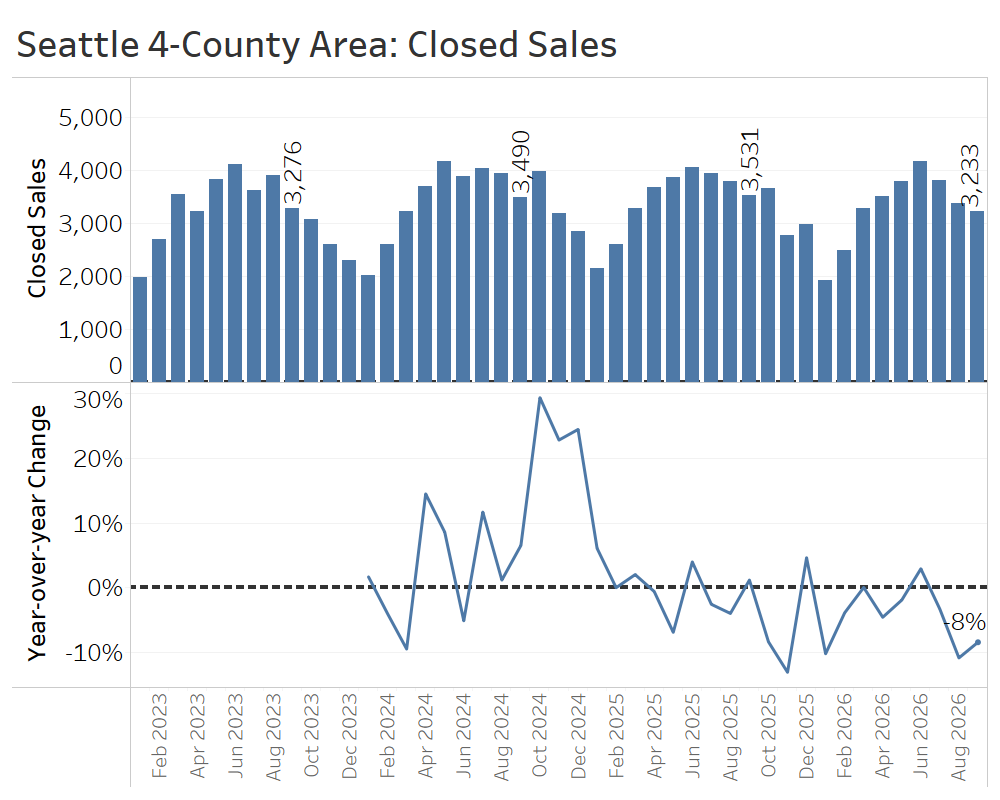
Closed sales declined throughout the third quarter. September recorded 3,233 closed sales, down 8% from a year earlier, following similar year-over-year declines in July and August. Total closed sales for the third quarter were down 7% compared with Q3 of 2025.
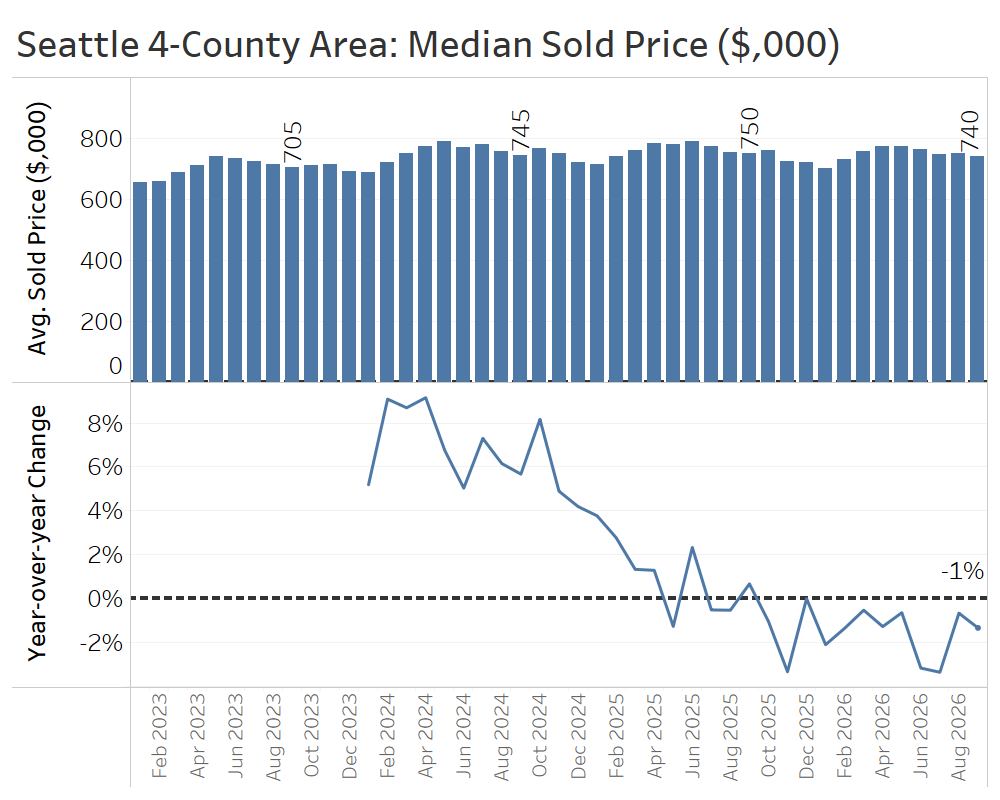
Softer demand and elevated supply contributed to a modest decline in prices. The median sold price was $740,000 in September, 1% below its year-ago level, and year-over-year price growth remained negative throughout the third quarter.
Overall, Seattle-area buyers had more homes to choose from in the third quarter, while homes took longer to sell and both closed sales and median prices ended September below year-ago levels. Sellers continued to face stiff competition, making realistic pricing and strong presentation essential to attracting buyers.
Greater Portland Area (Multnomah, Washington, Clackamas, and Clark Counties)
The greater Portland area’s housing market remained relatively balanced in the third quarter. Active inventory finished September slightly above year-ago levels, while new listings remained modestly lower and homes took somewhat longer to sell.
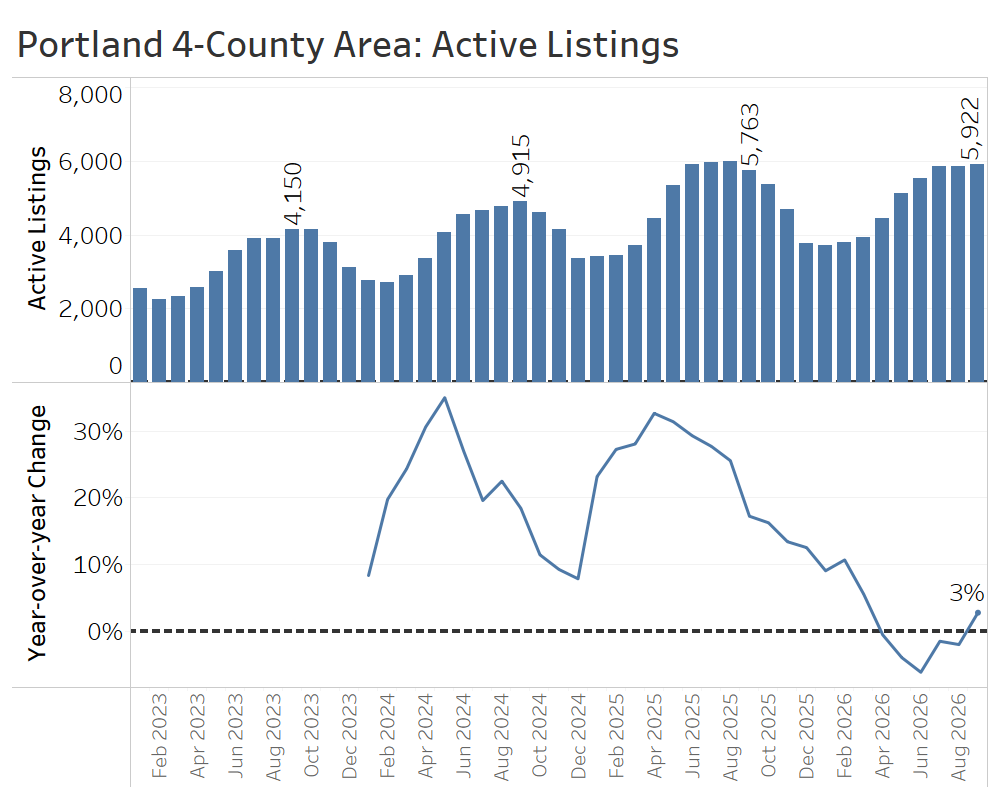
Active listings totaled 5,922 in September, up 3% from a year earlier. Inventory rose steadily from June through September, reversing the year-over-year declines seen earlier in the summer.
Over the summer, new listings tracked closely with year-ago levels, leaving the third-quarter total up just 1% year over year.
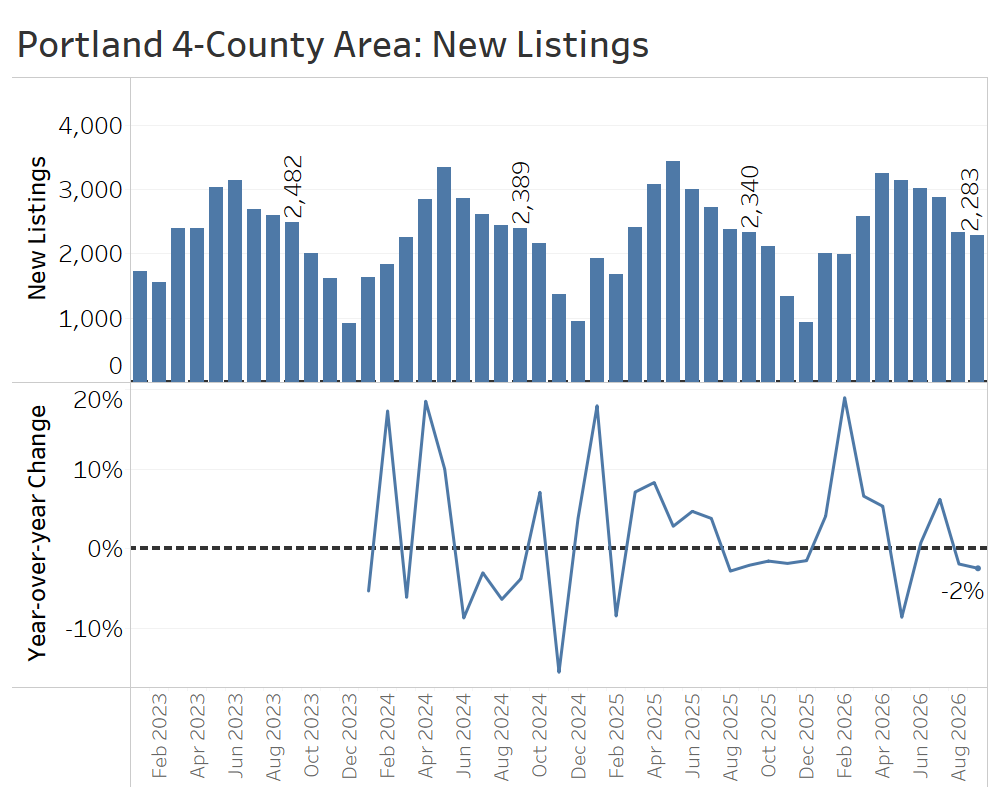
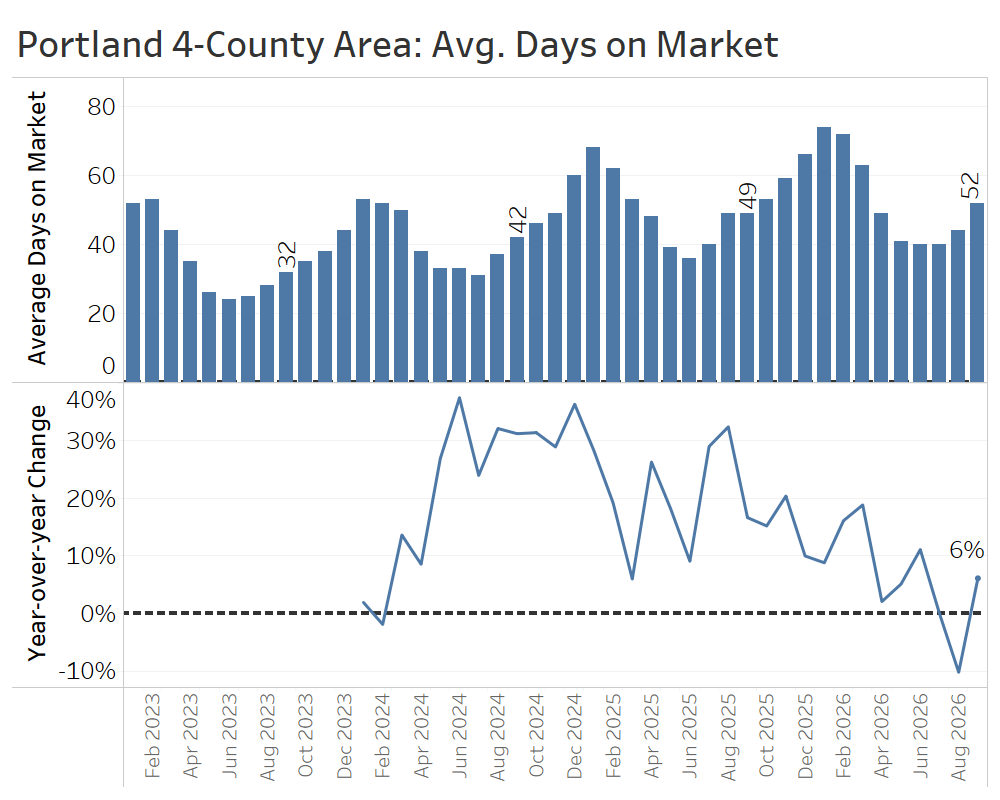
Average days on market increased over the third quarter, rising from 40 days in June to 52 days in September. September’s average was three days higher than a year earlier, following a brief drop below year-ago levels in August.
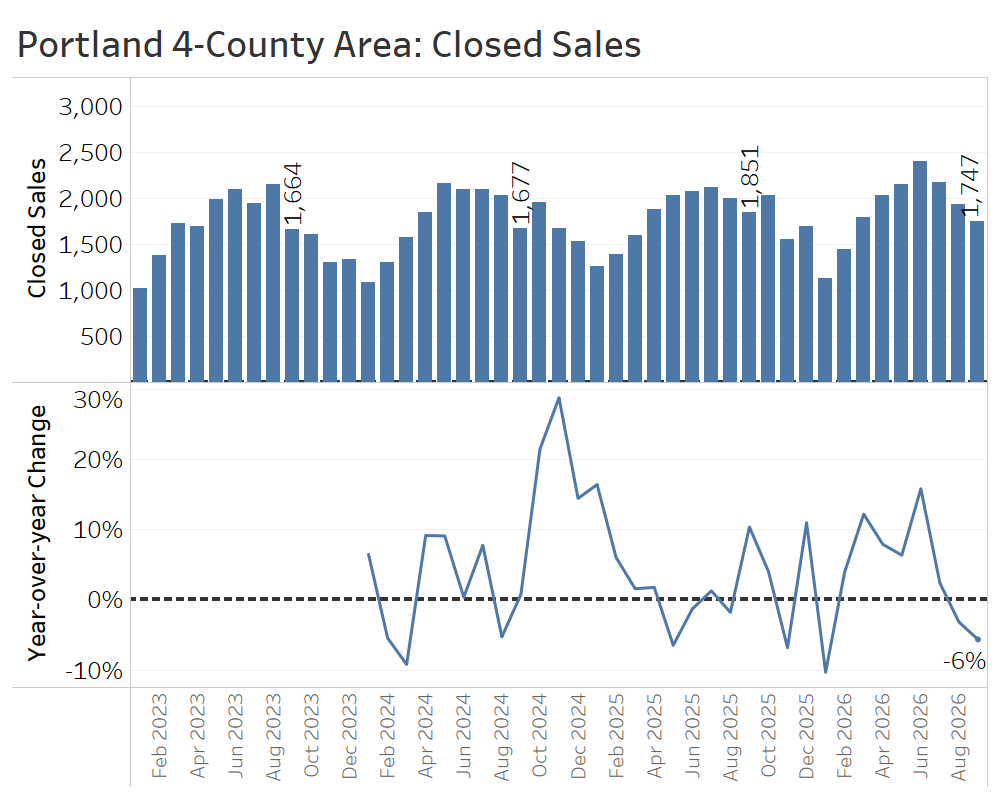
The Portland area’s run of sales growth ended in the third quarter. Closed sales dipped below year-ago levels over the summer, finishing the quarter 2% lower than in Q3 2025. Higher borrowing costs likely contributed to the cooldown in sales activity.
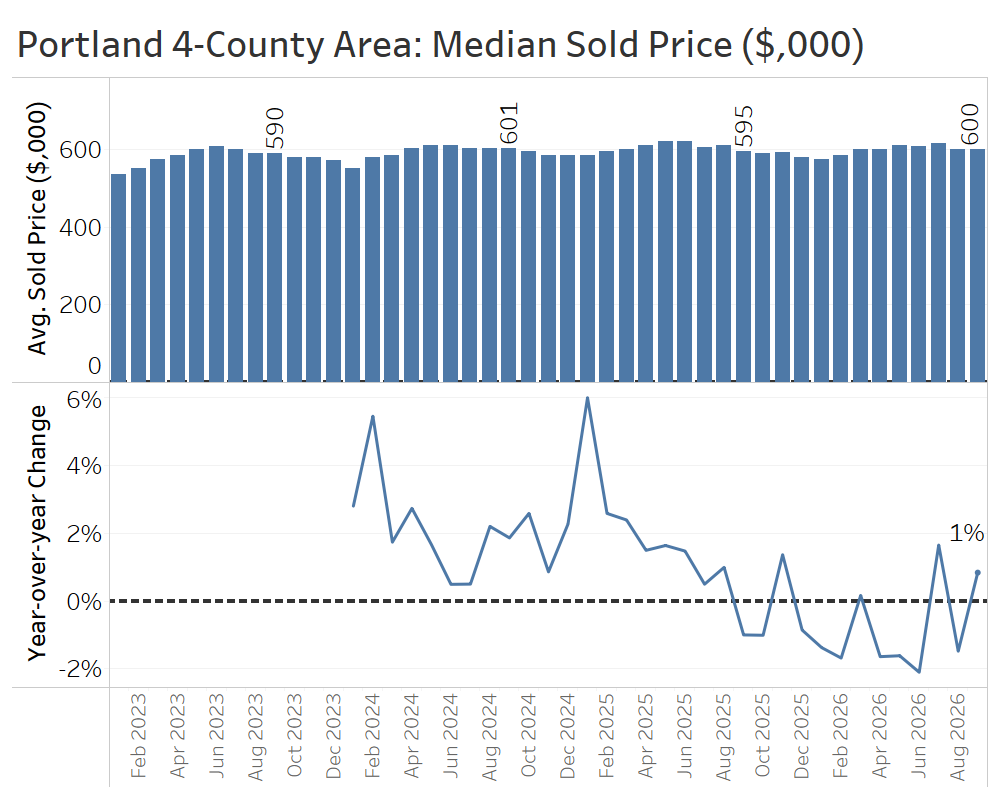
Median sold prices stabilized and remained near year-ago levels throughout the third quarter. The median price was $600,000 in September, up 1% from a year earlier, following a 1% increase in July and 1% decline in August.
Overall, the Portland area’s housing market was relatively balanced in the third quarter. Inventory finished modestly above year-ago levels, while new listings and closed sales softened, and homes took somewhat longer to sell. Median sale prices, however, held steady.
Greater Sacramento Area (Sacramento, Yolo, El Dorado, and Placer Counties)
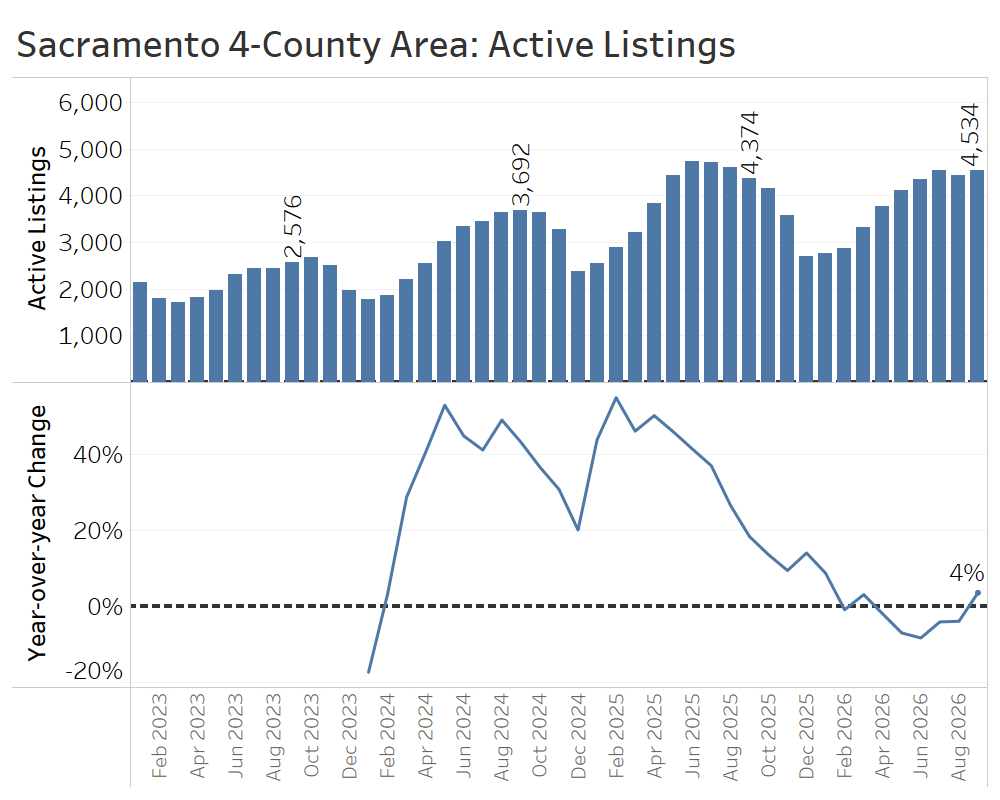
The greater Sacramento area’s housing market swung modestly in buyers’ favor in the third quarter of 2026, following more balanced conditions in the second quarter.
Year-over-year inventory declines from the second quarter gradually gave way to growth, with active listings finishing September 4% above year-ago totals.
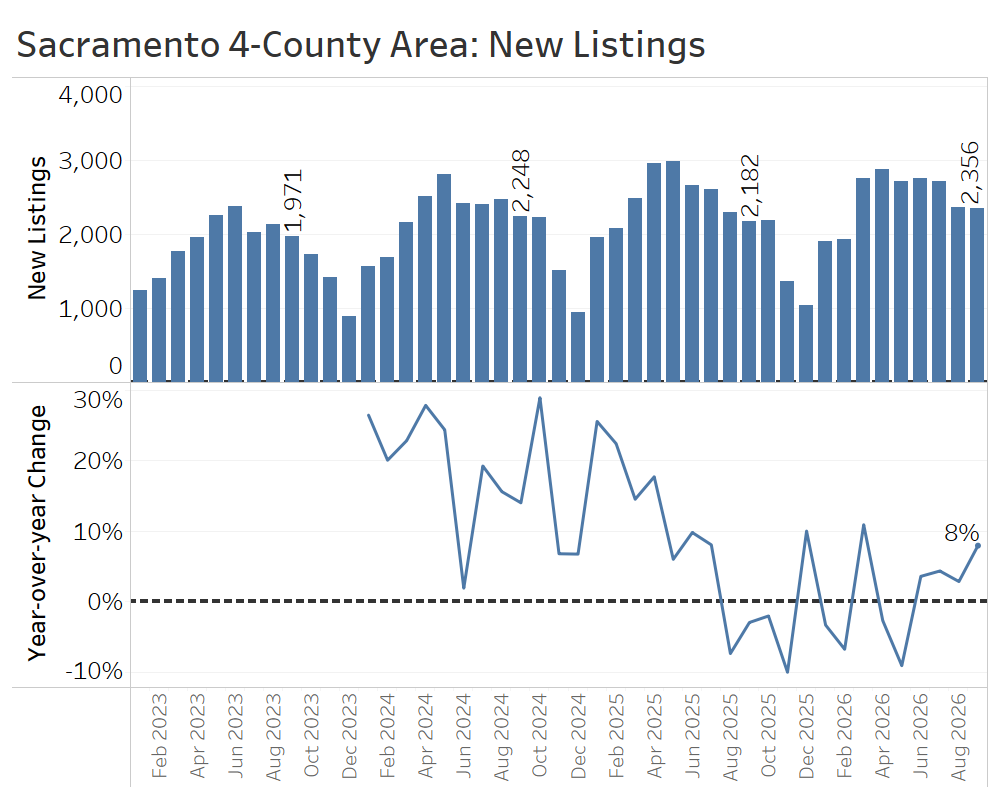
Inventory growth in the third quarter was driven in part by an increase in new listings, which were up 5% for the quarter and 8% in September compared with the same periods last year.
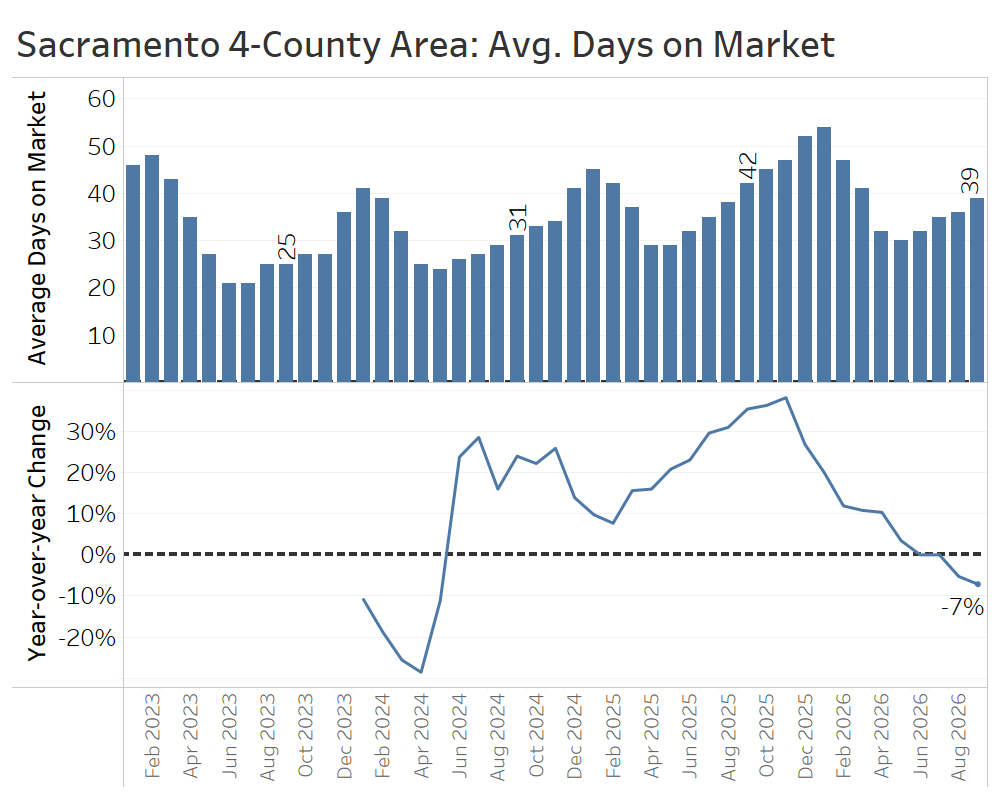
In more encouraging news for Sacramento-area sellers, homes continued to sell faster than a year earlier, with average days on market in September down three days from September of 2025.
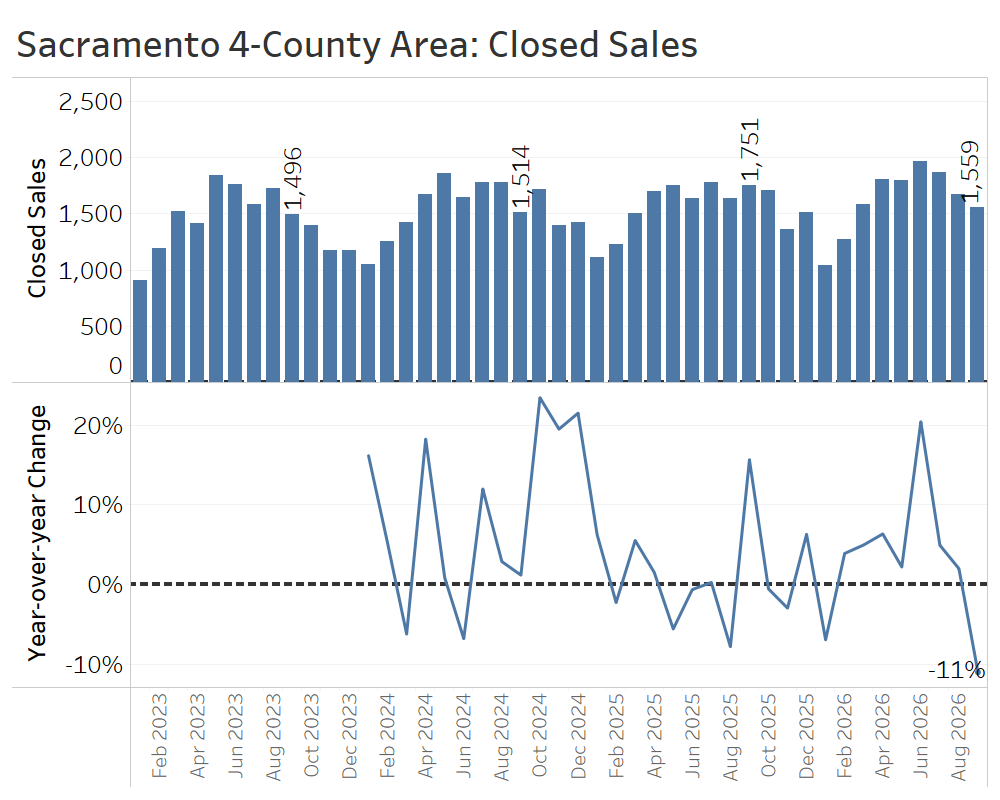
Closed sales softened modestly over the third quarter, although September saw a sharper year-over-year decline of 11%. For the quarter overall, closed sales were down just 1% compared with Q3 2025.
The median sale price climbed back up to $600,000 in September, up 2% from its year-ago level of $587,000, and very close to the $598,000 seen in September of 2024.
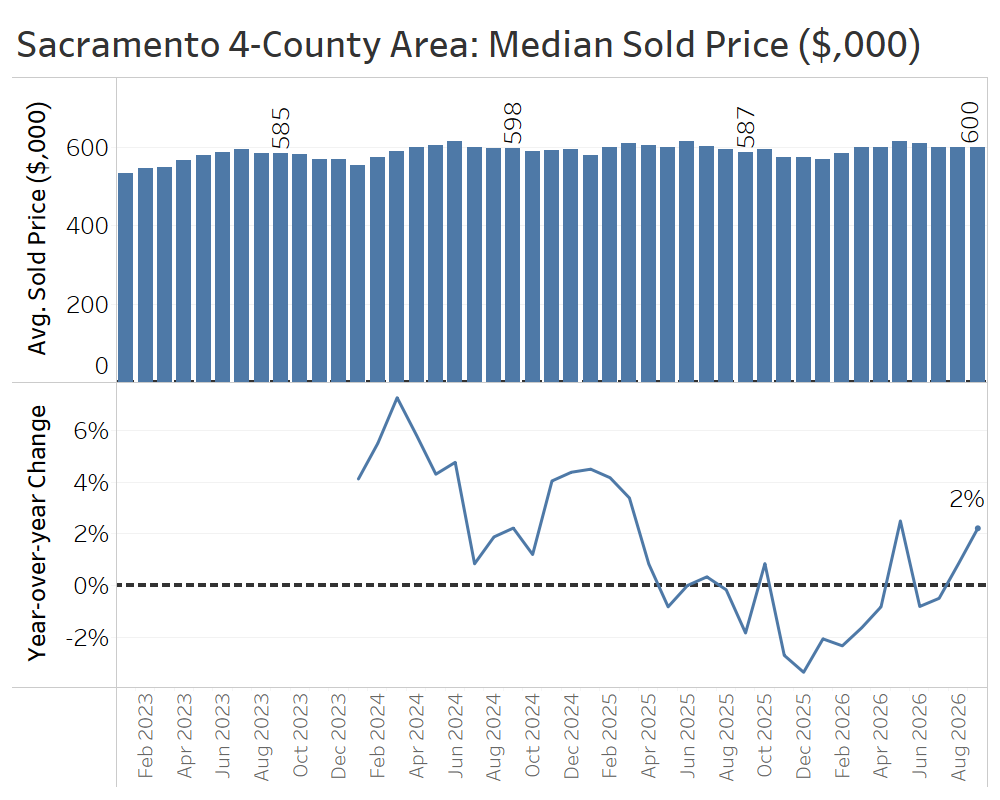
Overall, Sacramento’s housing data suggest that a recovery in demand may have stalled in the third quarter amid rising interest rates and economic uncertainty. Buyers who can afford to stay in the hunt will find plenty of options to choose from in the fall housing market.
Northwest Washington (Skagit, Whatcom, San Juan, and Island Counties)
Market conditions in the four northernmost counties of Western Washington continued to shift in buyers’ favor during the third quarter.
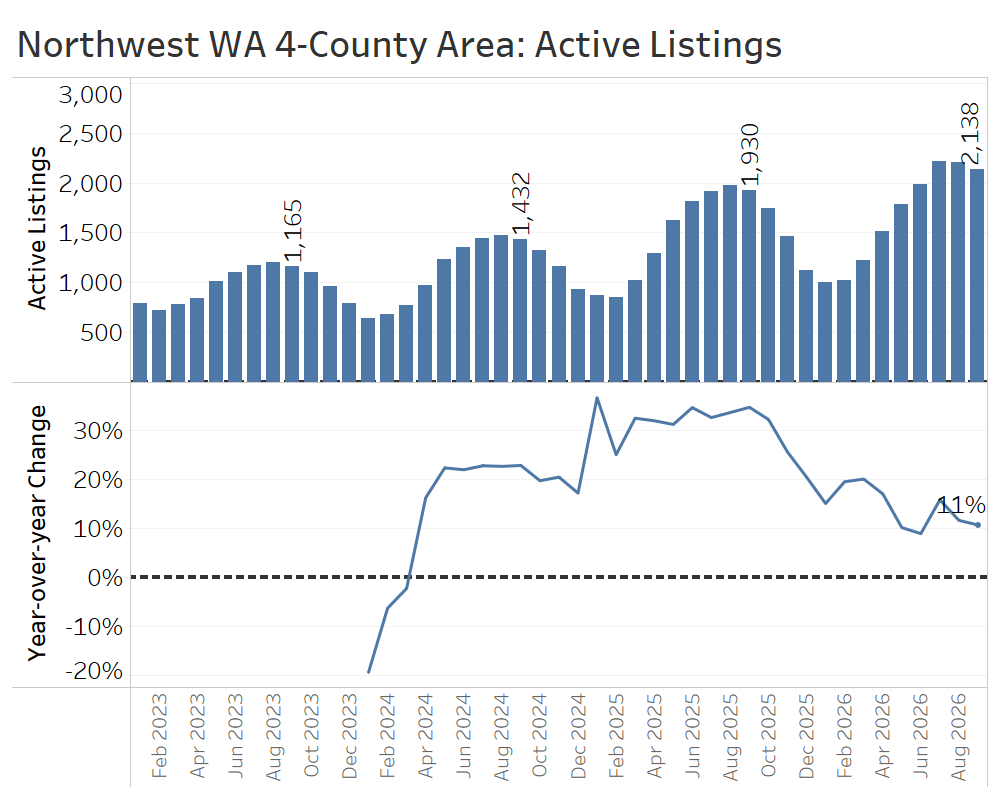
Active listings in September were up 11% from a year earlier, continuing a steady trend of roughly 10% year-over-year inventory growth that has persisted throughout 2026.
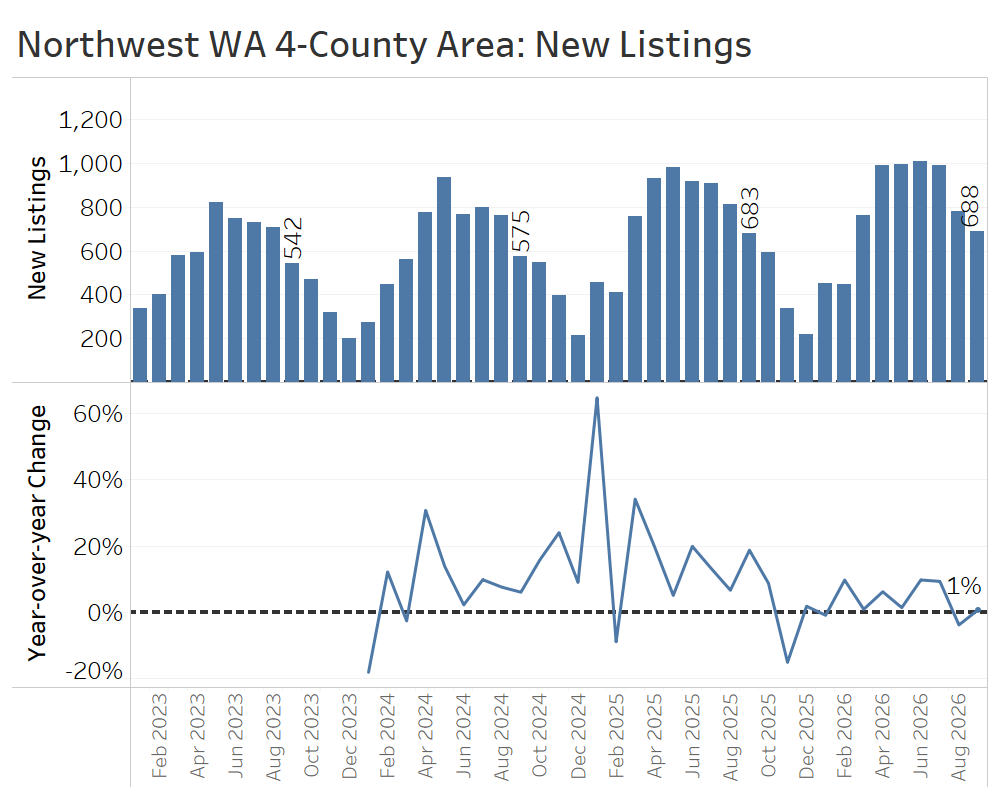
New listings slowed toward the end of the third quarter, perhaps reflecting sellers’ hesitation to list in a buyer’s market. Strong growth in July helped offset that slowdown, leaving new listings for the quarter up 2% compared with Q3 2025.
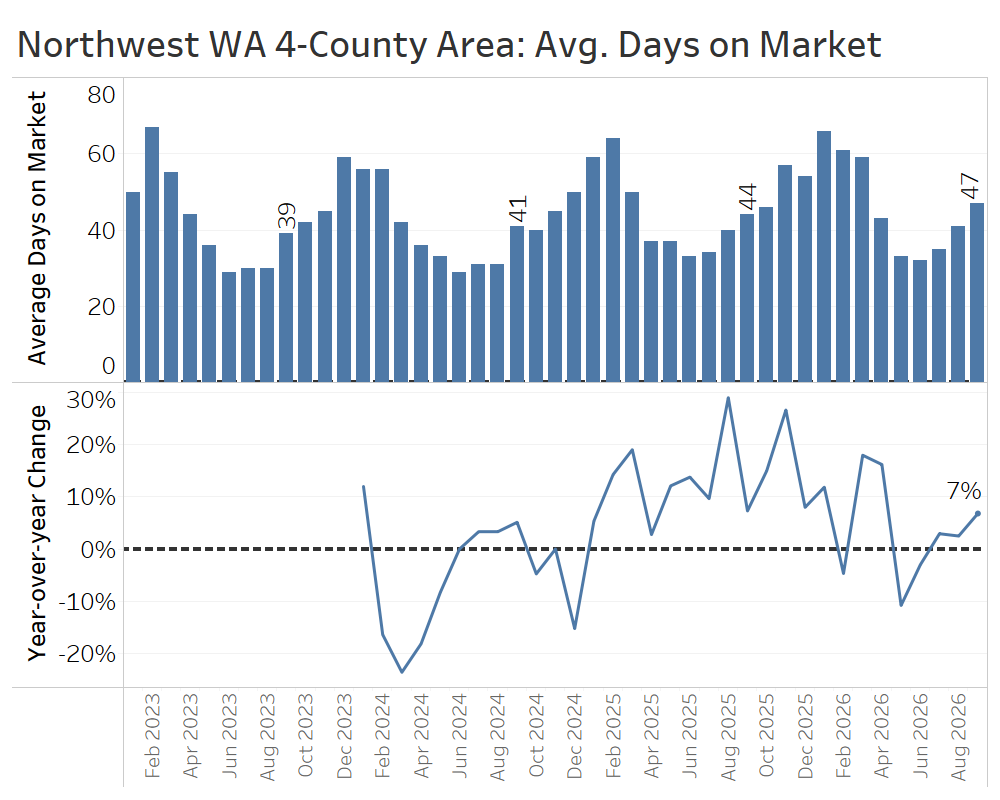
Days on market climbed above year-ago levels during the third quarter, reaching 47 days for the average home sold in September, up from 44 days a year earlier. Sellers who wait that long without receiving a satisfactory offer may find themselves needing to cut their asking price.
After a strong June, closed home sales fell throughout the third quarter, both month over month and year over year. September sales were down 15% from a year earlier, while the third-quarter total finished 9% below the same period in 2025.
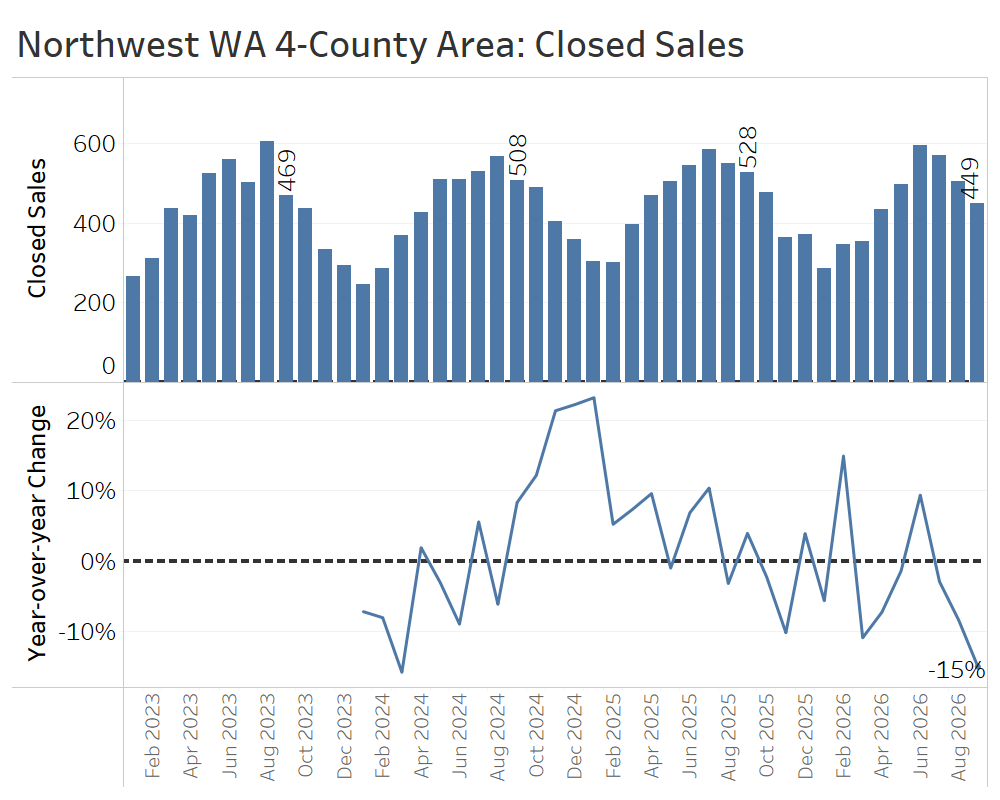
Remarkably, despite the drop in sales activity, median sale prices held steady, ending the quarter at almost exactly the same price as last September.
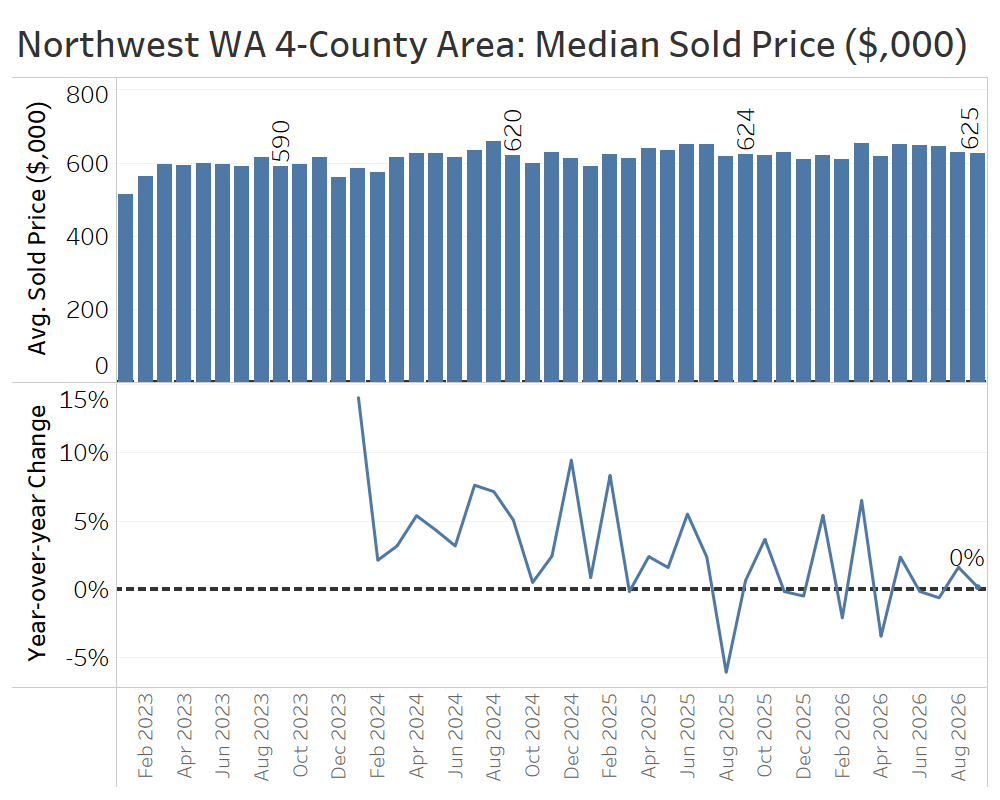
Overall, Northwest Washington’s third-quarter data suggest that homebuyer demand continued to cool amid higher interest rates. Growing inventory, longer selling times, and declining closed sales point to a market increasingly tilted in favor of buyers.
Spokane, WA and Coeur d’Alene, ID Area (Spokane and Kootenai Counties)
The greater Spokane-Coeur d’Alene region, spanning the Washington-Idaho border, continued to look balanced in the third quarter.
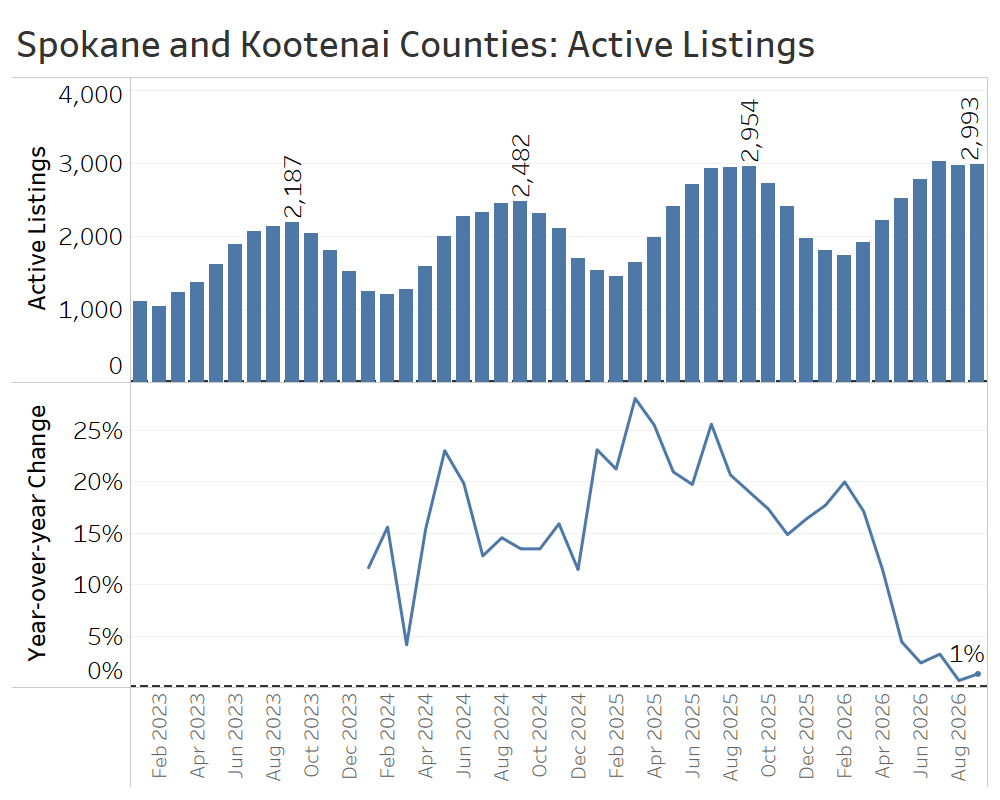
Active listings throughout the third quarter just slightly exceeded year-ago levels, ending the third quarter about 1% higher than at the end of September last year.
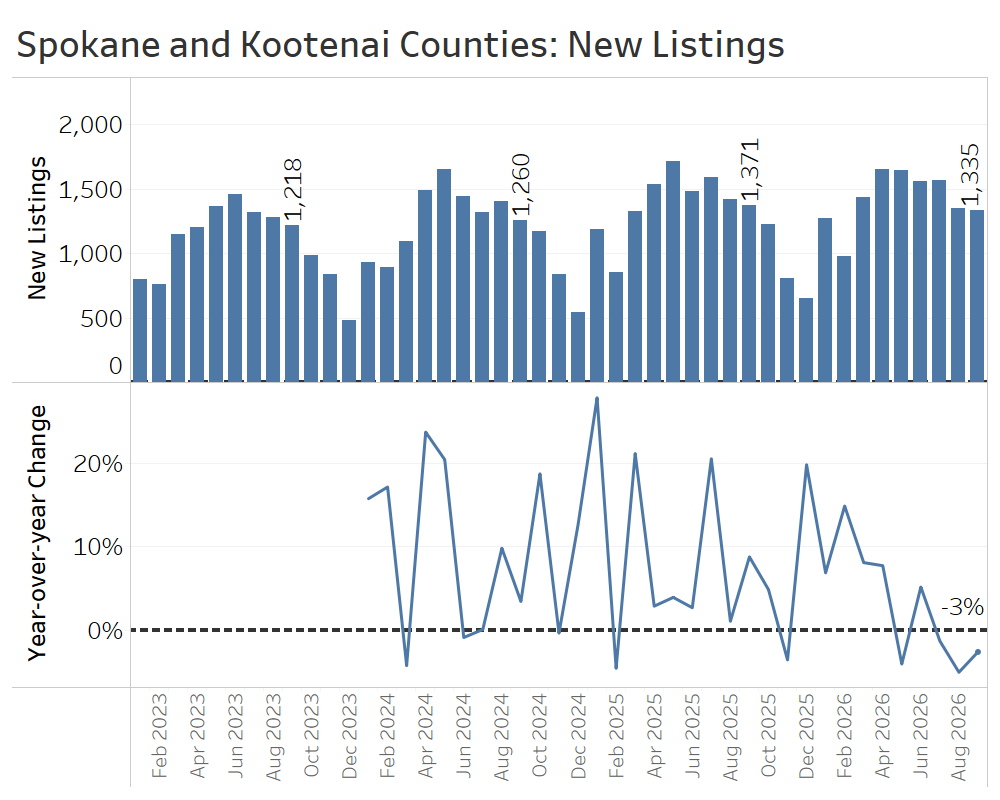
New listings dipped slightly, running 3% below year-ago levels for the quarter as a whole. There’s no sign of increased seller pressure on the market in this data series.
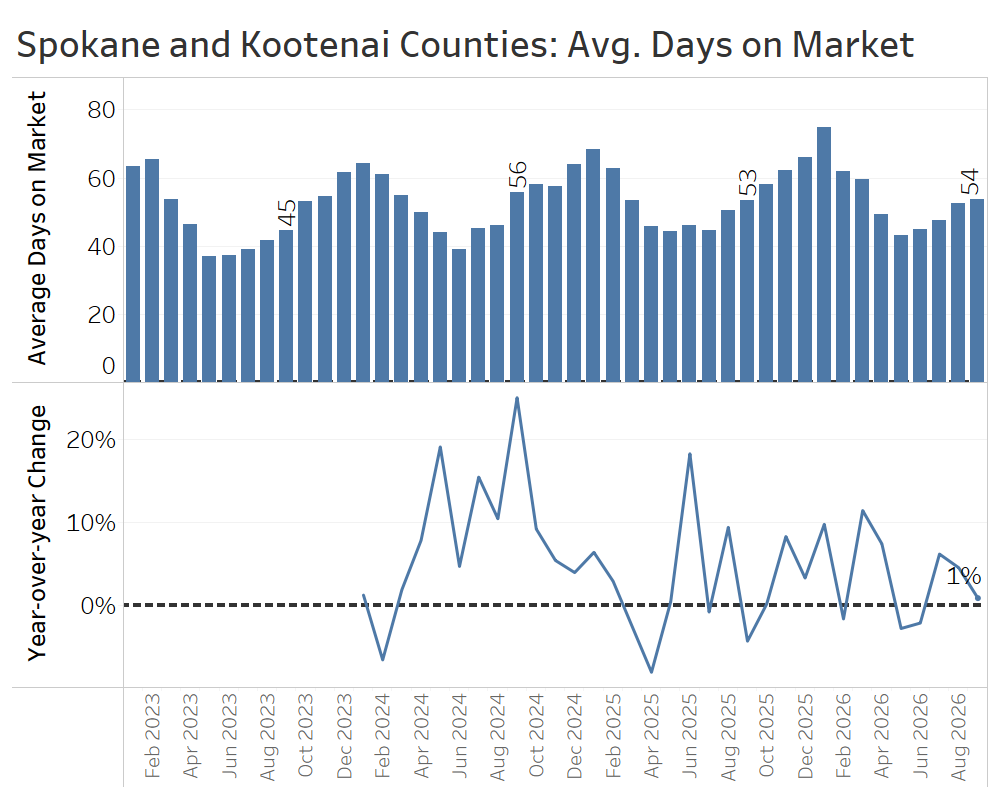
Days on market slightly exceeded year-ago levels in each month of the third quarter, but the change is too modest to indicate much of a trend yet.
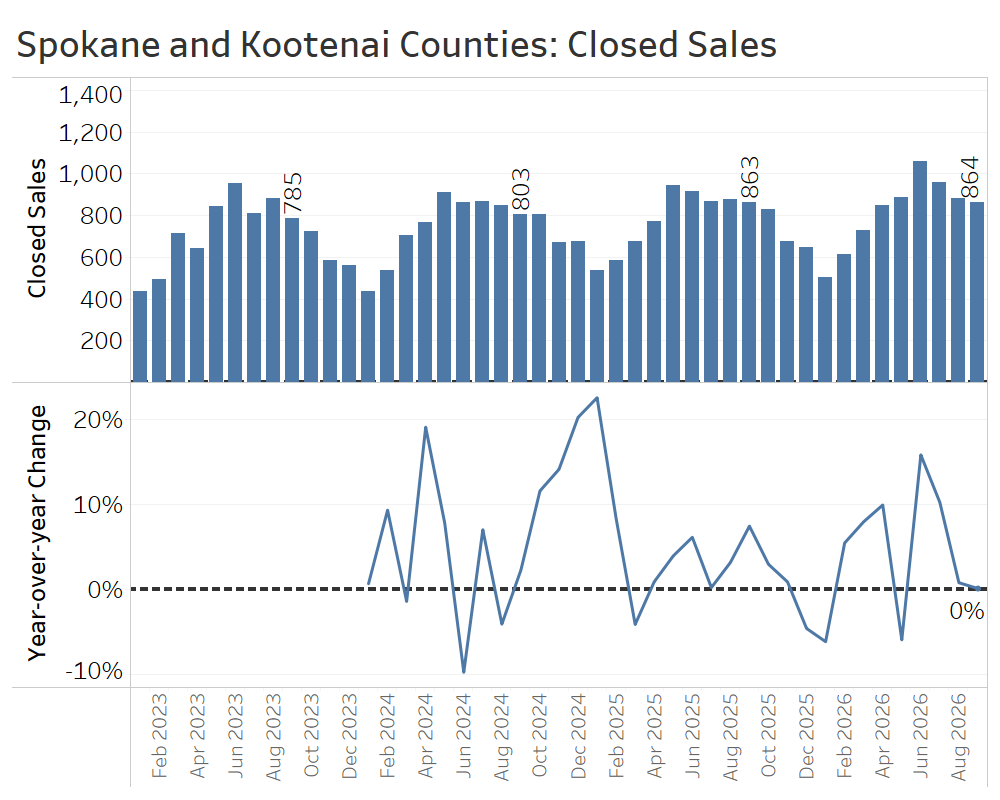
Closed sales for the quarter increased 4% year over year, with nearly all of that growth coming in July. Sales in August and September were virtually unchanged from year-ago totals.
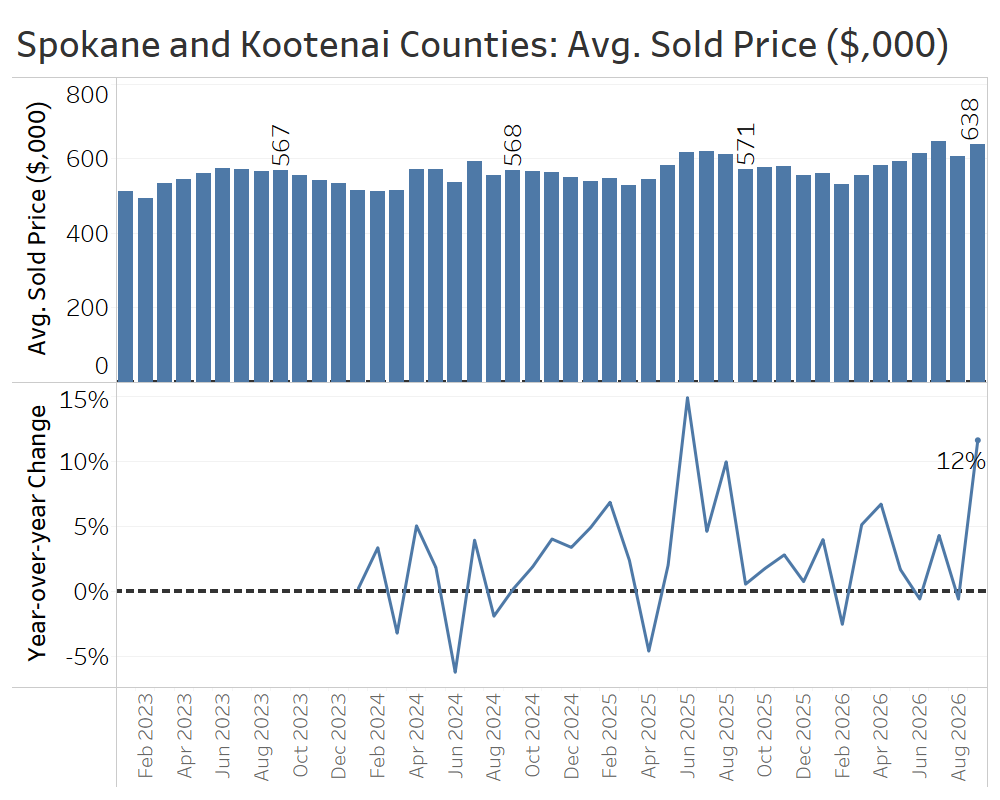
Average sale prices were roughly flat in August before jumping sharply in September to $638,000. The increase was driven by a 5% gain in Spokane County and a whopping 27% gain in Kootenai County compared with September 2025. The jump in Kootenai County is unlikely to reflect an underlying trend and was probably driven by a handful of high-end sales. Median sold prices rose much less in both counties, increasing 1% in Spokane County and 6% in Kootenai County.
Altogether, the greater Spokane-Coeur d’Alene area housing markets continued to look balanced through the third quarter, with stable inventory and sales very close to year-ago levels. Demand in the region has stayed resilient in the face of higher mortgage rates, at least through September.
Salt Lake County, Utah
In the third quarter of 2026, Salt Lake County’s market shifted modestly back towards buyers after moving in sellers’ favor earlier this year.
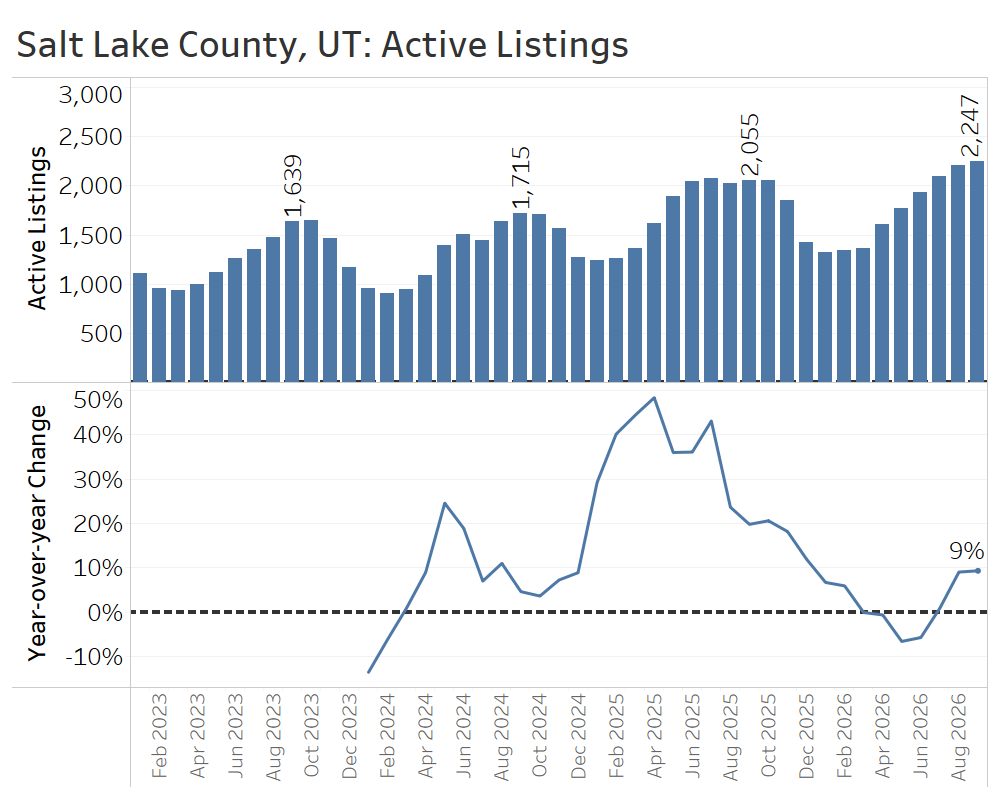
Active listings ended September 9% above year-ago levels, with inventory growth resuming after a few months of declines this spring.
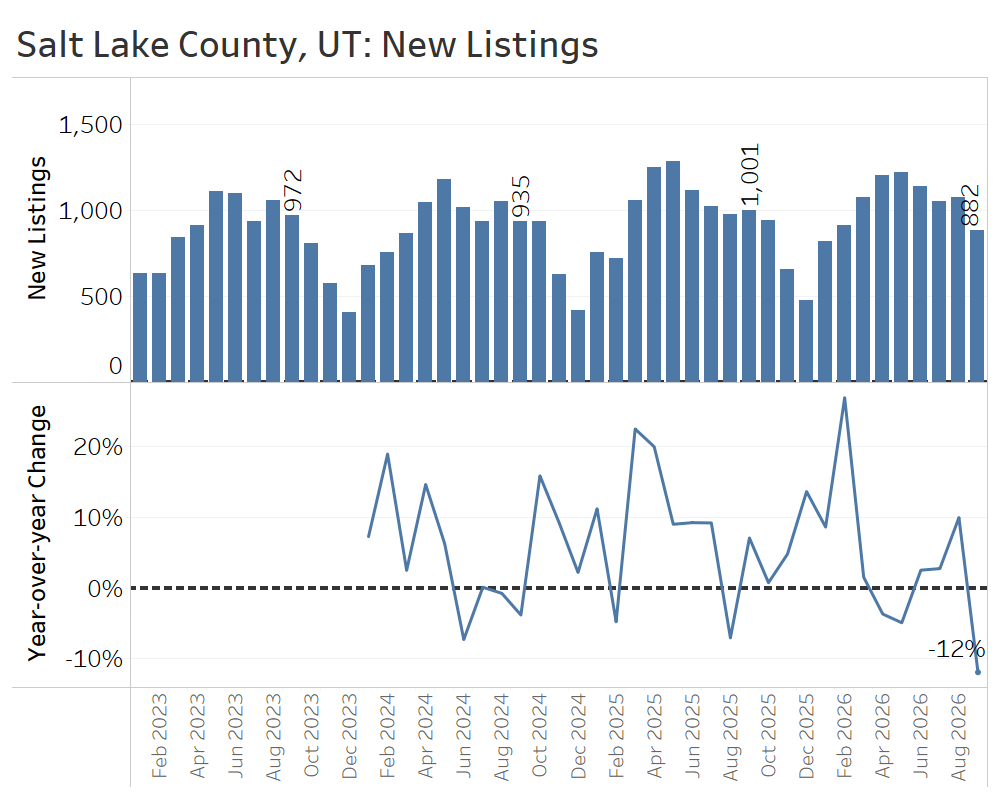
New listings in the third quarter were nearly unchanged from a year earlier, totaling just over 3,000. September listings, however, saw a dramatic dropoff of 12% below September 2025 levels. Data from the fourth quarter should help clarify whether that decline signals a broader trend or is simply a temporary blip.
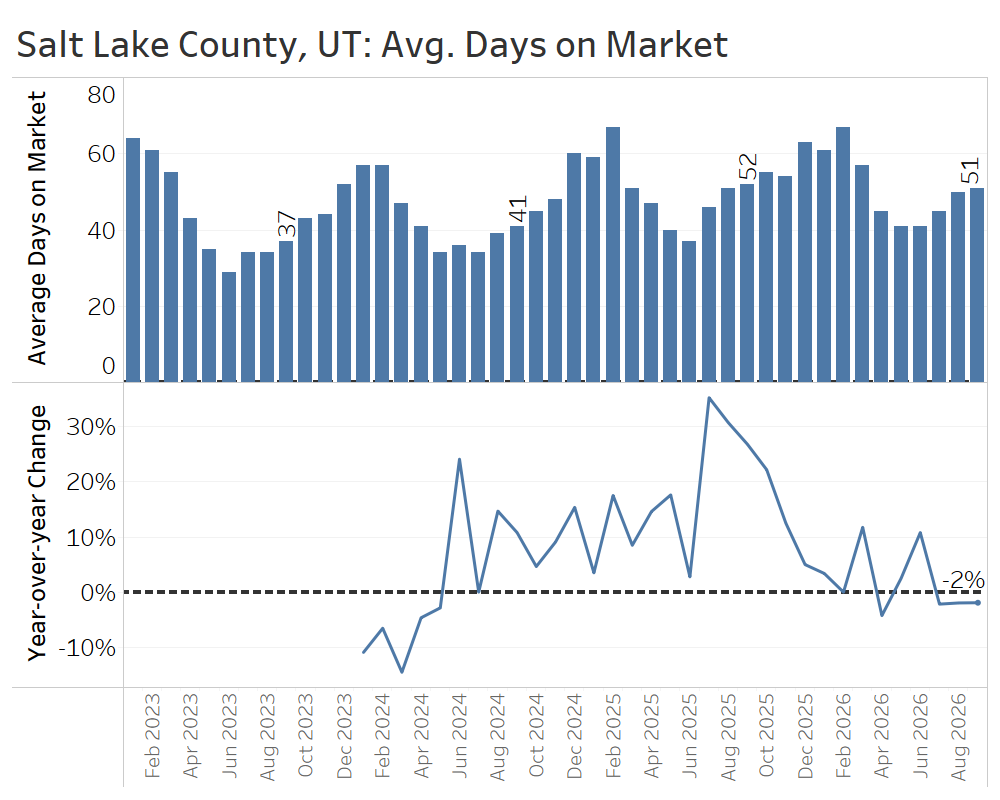
Days on market closely matched year-ago levels, down by just one day from 52 last September to 51 days this September.
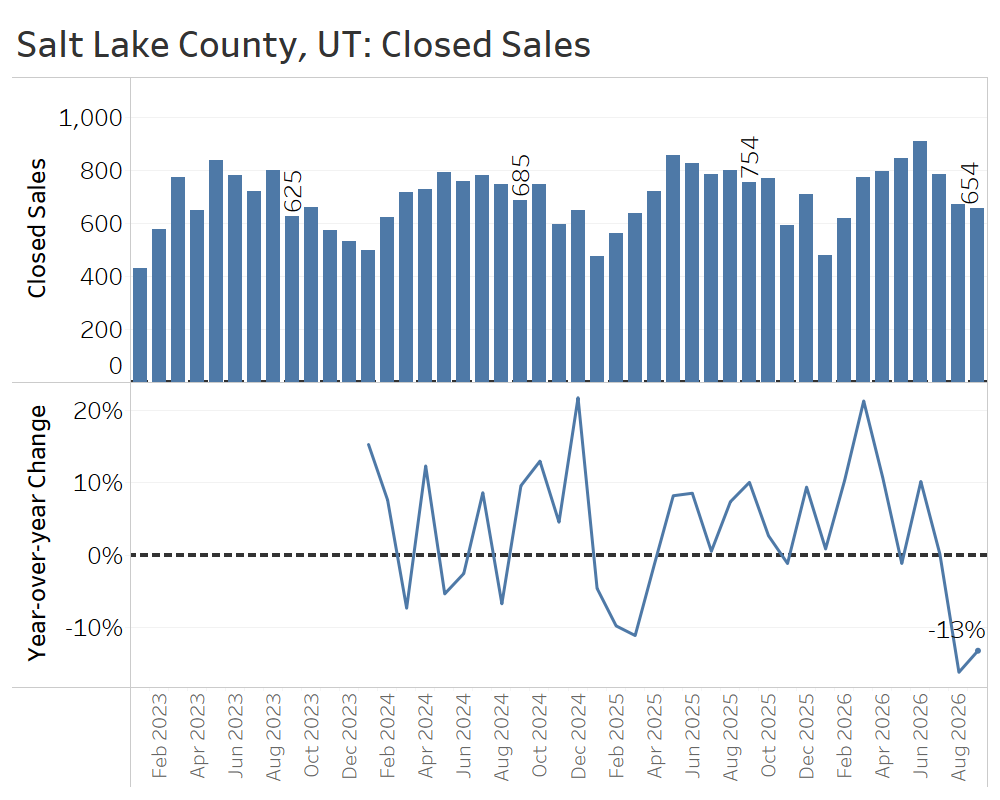
After an impressive 5% year-over-year increase in the second quarter, closed sales declined in the third quarter, finishing about 10% below the same period last year.
Median sale prices continued to rise year over year throughout the third quarter, although the pace of growth slowed to just 2% by September.
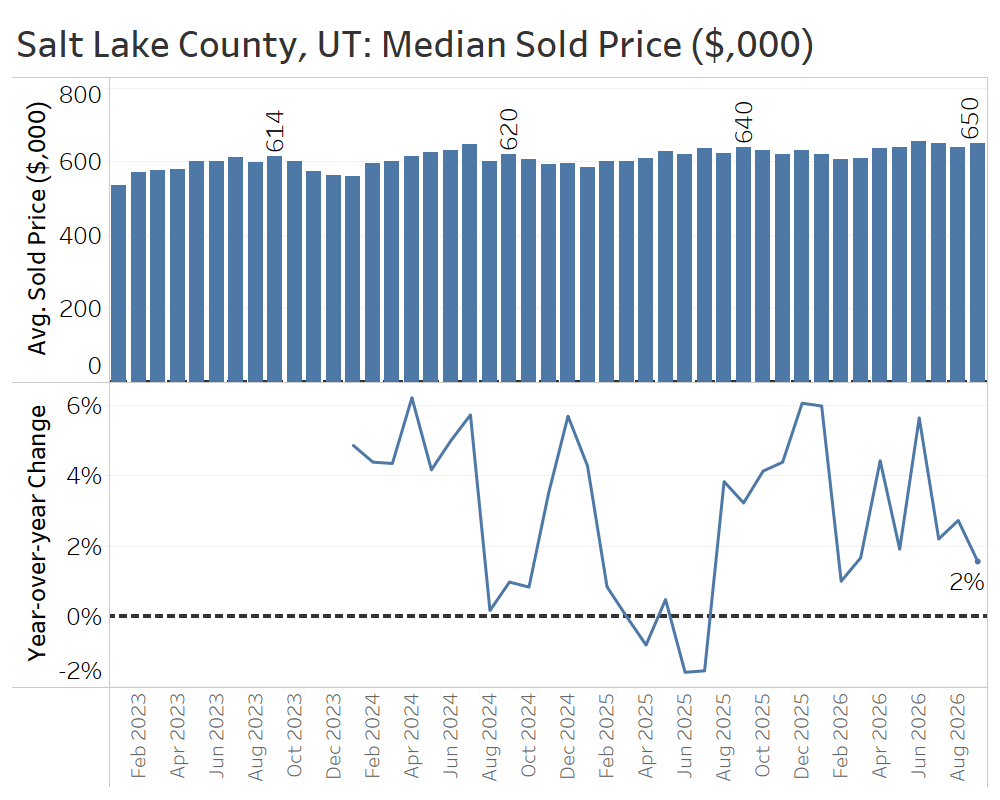
The third quarter marked a sharp reversal from Salt Lake County’s stronger demand in the second quarter. In particular, closed sales fell well below year-ago levels as buyers appeared to pull back amid rising interest rates and inflation. Still, home prices have held onto their gains, suggesting sellers are holding firm on asking prices while waiting to see whether demand rebounds.
Conclusion:
In the third quarter of 2026, homebuyer demand began to buckle under the pressure of rising mortgage rates and widespread inflation. Inventory growth accelerated or shifted from negative to positive in nearly every market covered in this report, as buyers pulled back while sellers kept bringing homes to the market. Many would-be buyers have already waited years in hopes of better conditions, and with mortgage rates reaching their highest levels in three years, many may put their plans on hold for another season.
As the market enters the fourth quarter, traditionally the quietest time of year for home sales, buyers who can afford to forge ahead despite higher mortgage rates will find a plethora of options. Sellers, meanwhile, face a difficult choice: try to find the right buyer now or wait for the spring selling season in hopes of stronger demand.
With mortgage rates and the economy especially difficult to predict amid ongoing geopolitical turmoil, sellers need to lean on their agents’ expertise more than ever. In a changing market, realistic pricing and presenting a home in its best possible light through staging, photography, and marketing can make a meaningful difference in attracting buyers.
Sources: TrendGraphix analysis of NWMLS, RMLS, Spokane MLS, Coeur d’Alene MLS, MetroList MLS, and Wasatch Front MLS data. All charts are restricted to single-family residential home listings and sales.