Facebook
 X
 Pinterest
 Copy Link
Hi, I’m Jeff Tucker, principal economist at Windermere Real Estate, and these are the numbers to know, right now.
The first number to know is 4.2%, the unemployment rate in September.
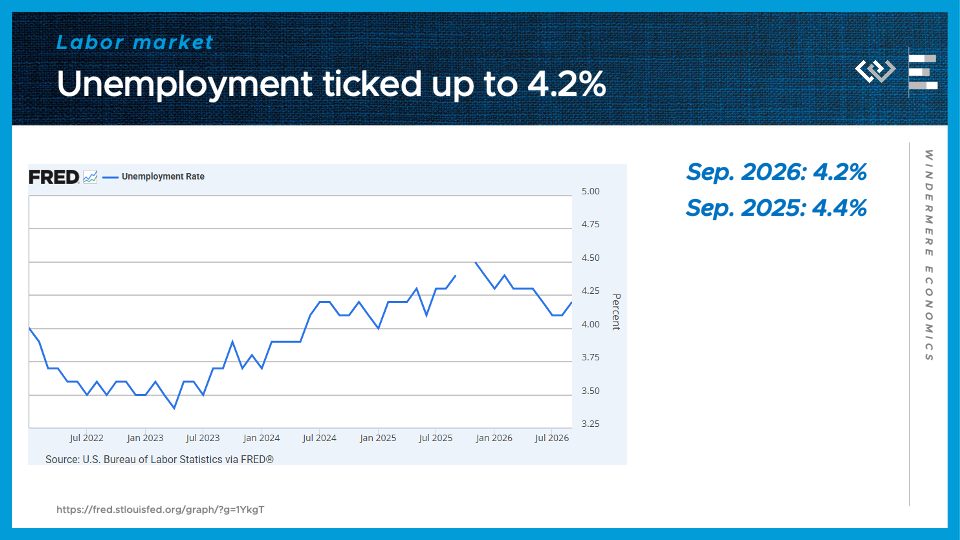
That is up slightly from recent months, but still below the 4.4% observed one year ago. This might be an early sign of a labor market cooldown, but it’ll take more data to tell.
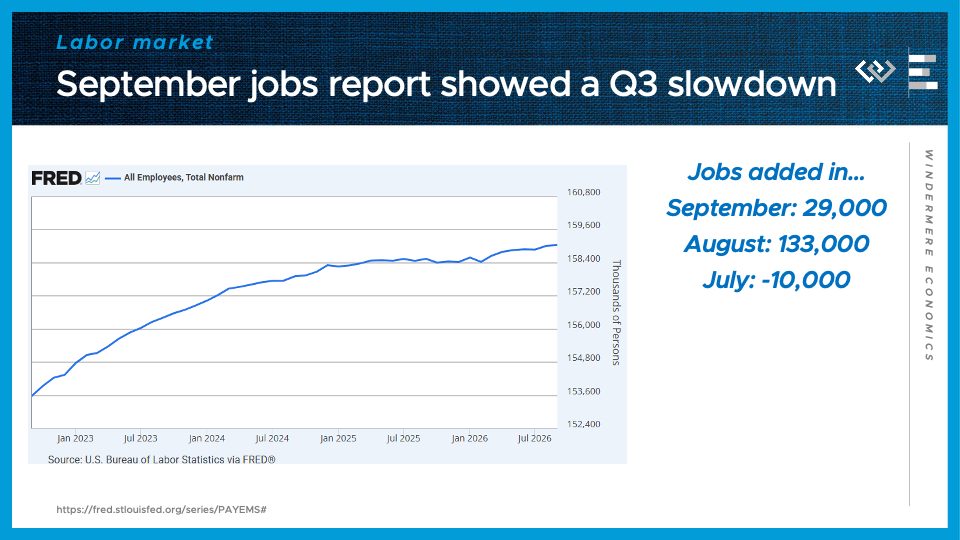
The September jobs report also showed employers added just 29,000 jobs in September, following a downwardly revised 133,000 in August and a decline of 10,000 in July. Taken together, that looks like a return to last year’s “low-hire, but low-fire” economy, and less like the hot labor market seen earlier this year.
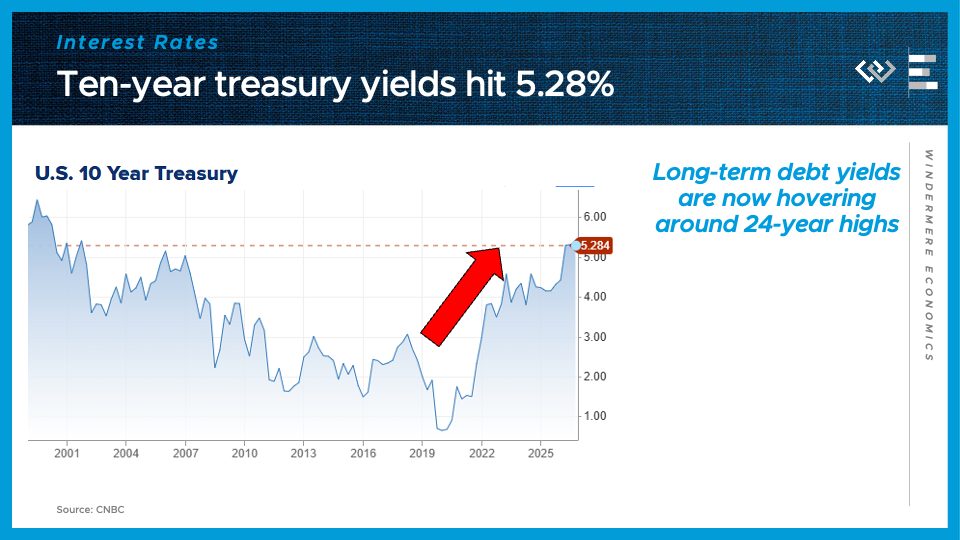
The next number to know this month is 5.28%. That is where the yield on the 10-year U.S. Treasury has climbed, putting this key benchmark near a 24-year high. One proximal cause is weak demand at Treasury auctions, but fundamentally, investors see a lot of high-yielding investment opportunities in the stock market and corporate debt markets, and government debt can’t find buyers without offering some comparably high yields.
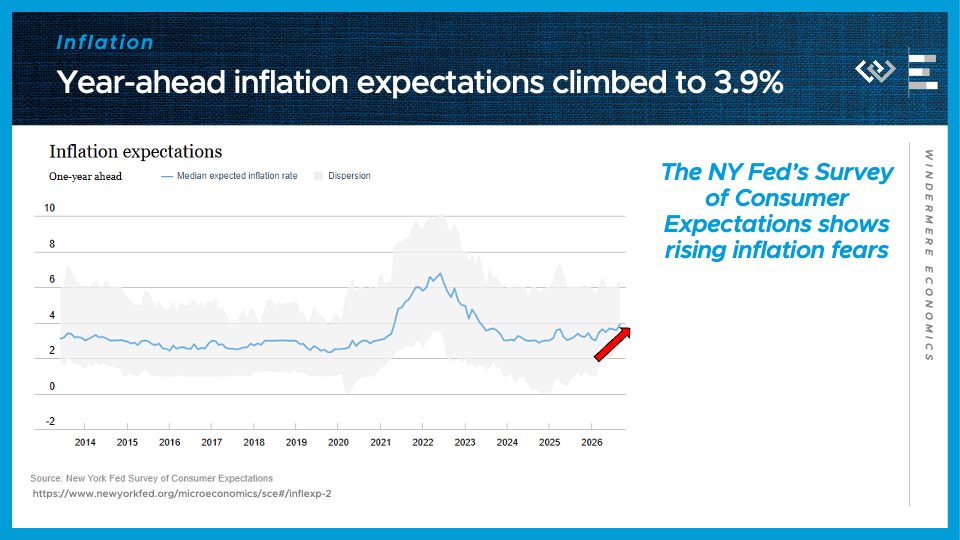
Another reason for higher yields, though, is in our next number to know: 3.9%. That is the median year-ahead inflation expectation in the New York Fed’s latest Survey of Consumer Expectations. Fears of higher future inflation can become self-reinforcing as households and businesses adjust their spending plans and raises, which is the kind of inflation loop the Fed is particularly keen to shut down by hiking interest rates.
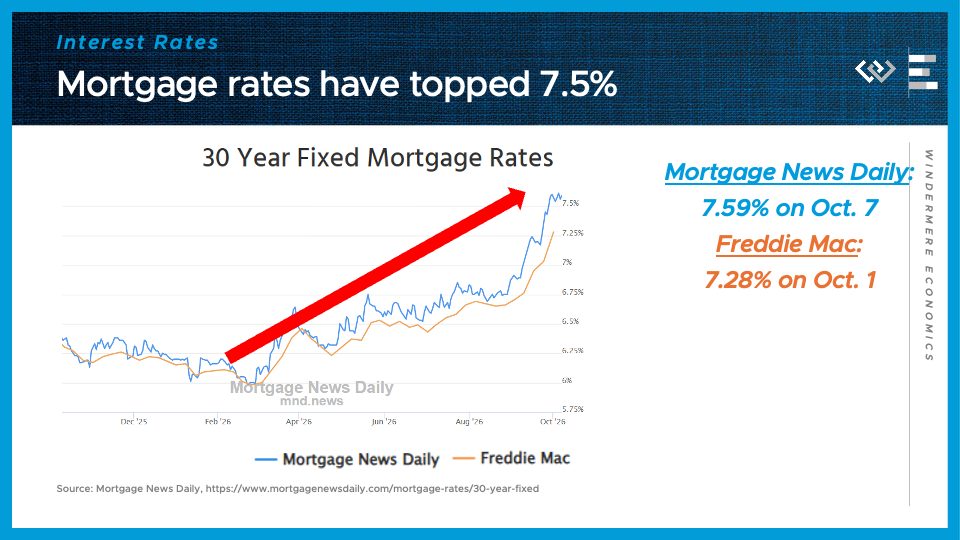
Those higher Treasury yields are flowing directly into higher mortgage rates. Mortgage News Daily reported a 30-year fixed rate of 7.59% on October 7, while Freddie Mac reported 7.28% on October 1. Mortgage rates have climbed dramatically, up 1 and half points since February, and about half that gain came just in the 6 weeks since late August. This interest rate shock has begun to put a damper on homebuyer demand.
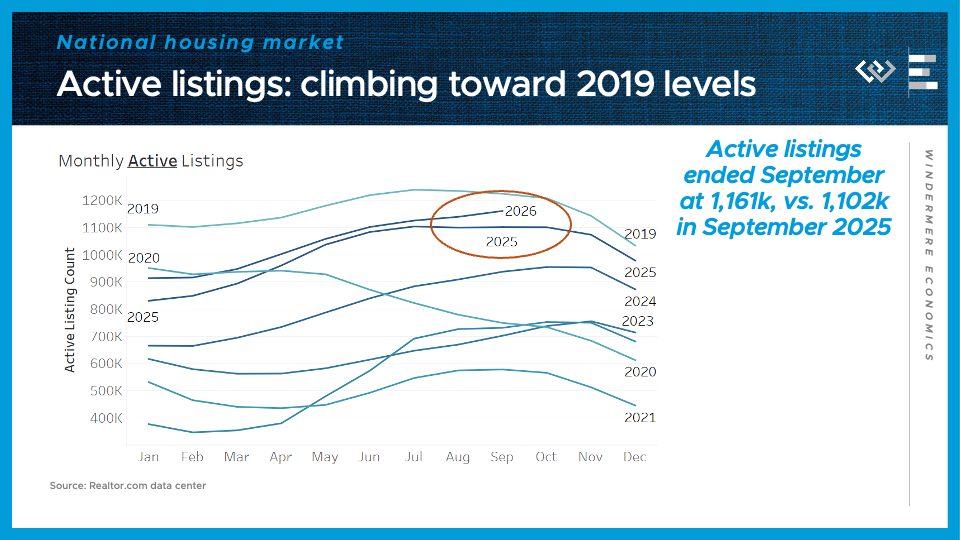
That brings us to the national housing market, where active listings reached 1,161,000 at the end of September. That is up from 1,102,000 in September 2025 and puts inventory on a path toward the levels seen in 2019, before the pandemic reshaped the market.
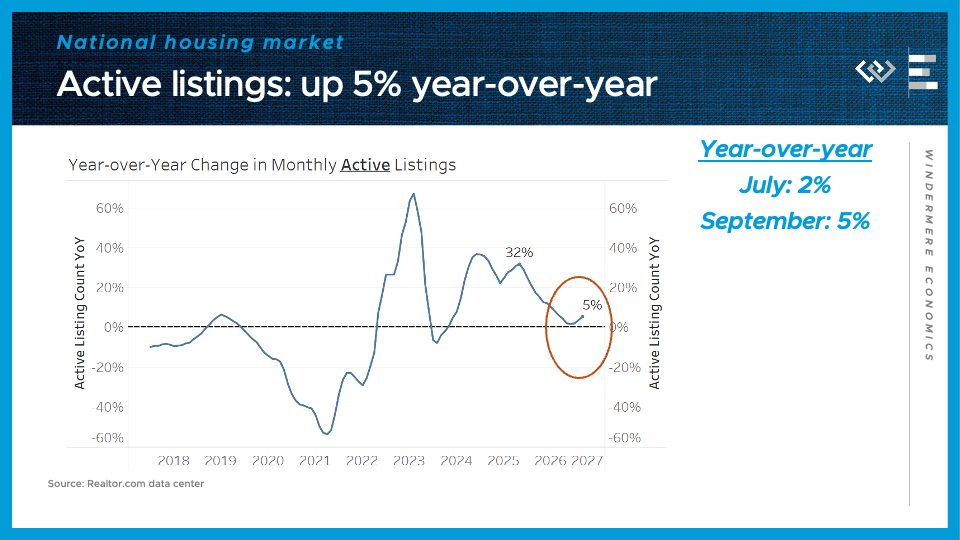
It’s a year-over-year gain of 5%, accelerating from just 2% growth in July. This looks like the early signs of a sales cooldown in the wake of higher borrowing costs and uncertainty in the third quarter. It also means that buyers who stay in the hunt will have abundant options, and stronger negotiating power, when shopping this fall.